
Tools & Capabilities
dsh-quant
pengpengyi92/dsh-quant · ★ 69
 pengpengyi92Curated
dsh plugin: quantitative tools for agents — market data (Binance public API), technical indicators (SMA/EMA/RSI/MACD/Bollinger/ATR) and MA-crossover backtest
Manifest details
安装
dsh plugin --profile web add github:pengpengyi92/dsh-quantGitHub 源码安装:首次需按提示配置 allowBuilds 构建授权后重试
For install and environment setup, plus plugin development tutorials, see DSH community docs ↗
Screenshots
README
Table of contents
- 🧩 Core Philosophy: Everything is a Plugin (quant edition)
- 🤖 AI-Native Is Deliberate (design statement)
- 🐍 Why Almost No Python?
- 🤖 For visiting agents
- Compatibility release status
- Quick Install (dsh users)
- 🚀 Product Experience: Three Minutes to a Full Quant Pipeline
- 🖥️ UI Workbench (dsh-quant-ui)
- ⌨️ CLI (dsh-quant terminal)
- Tools
- Typical chain (model's view)
- Backtest contract
- Alignment conventions
- Contract (defineTool)
- Model Experience
- What the model sees
- Token impact
- KV cache impact
- Release history (NEWS)
- Known limitations & roadmap
- Domain layout (PDAT→PET pipeline mapping)
- Quick start (after fork/pull)
- Build & use
- Verification
- ⭐ Support
- 🤝 Contribute & maintain
- 👤 About the author
- Compatibility contributors
- Test contribution under review
📣 Announcement archive: 2026-09-01 X open-source launch copy
🌐 Site: https://dsh-quant-site.pages.dev · ✅ Listed in (one-click install via dsh-market)




AI-native & DSH-native quant toolkit for every quant aspect — 59 tools · 6 domains (data / alpha / ML / risk / execution / ecosystem) · one end-to-end PDAT→PET research pipeline. Methods open, secrets internal.
🧩 Core Philosophy: Everything is a Plugin (quant edition)
dsh's philosophy is everything is a plugin; dsh-quant brings it to quant — open-sourcing the internal five-team paradigm (PDAT → PAAT → PCPT → PRT → PET) as five pluggable modules:
data plugin   dsh-data      market data / sources / quality  ← plug in Binance or your own data
alpha plugin  dsh-alpha     indicators / factors / eval      ← write your own alpha (internal alpha stays private)
model plugin  dsh-ml        backtests / ML/DL/RL framework   ← train your own models (internal research stays private)
risk plugin   dsh-risk      VaR / drawdown / options / bonds ← set your own risk limits
exec plugin   dsh-execution sim execution / fund / report    ← build your own trading system (paper or live)
- What's open is the paradigm: how modules compose, how contracts are defined (null alignment / no look-ahead / hand-computed tests), how results are validated — not the internal secrets
- You fill it in: product power = UI + strategies + data interfaces + DL/RL models + trading-system building, all self-assembled, all pluginized
- Infinite self-evolution: fill the framework with your modules → run paper/live → feed the ecosystem back — that's dsh-quant
Plugin call for proposals: Issue #27 (five modules × many plugins) — PDAT plugins, PET plugins, anything you can imagine 🐋
🤖 AI-Native Is Deliberate (design statement)
dsh-quant's primary consumer is the agent (the model), not the human — a deliberate choice from day one:
- Tool schemas are injected into the system prompt — every contract (args / outputs / alignment rules) is written from the model's perspective
- Equal-length null alignment — outputs match input length; leading window
positions are
null, so the model aligns by index and never pads - Canonical JSON + render separation — machines read structure, humans read prose
- All isConcurrencySafe — pure functions, no shared state; agents can call all 59 tools in parallel without interference
- Skill layer —
skill/quant-researchlets the model load the workflow itself
Full statement: Issue #14 "AI-native is deliberate".
🐍 Why Almost No Python?
A common question: a quant project without .py files? Answer: 0 Python files,
21 TypeScript source files, zero runtime dependencies — deliberate:
- dsh-quant is a dsh plugin running inside the harness's Node runtime: same process as the agent, composable by the Loader, reversible registration (HMR-safe) — TypeScript is the only natural choice
- Where Python is needed (akshare / tushare / baostock), use the channel knowledge
base (
quant_data_guide, 15 channels): dsh ships shell / subprocess capabilities, so the agent decides whether to spawn Python — dsh-quant carries no runtime - All numerical methods (indicators / backtests / options / bonds) are pure
functions with hand-computed baselines: zero deps, offline-verifiable,
npm testgreen anywhere
One goal: build the most usable AI-native quant repo 🐋
59 quant_* tools · 6 domains · 298 tests · zero runtime deps. Full positioning: pinned Issue #9.
🤖 For visiting agents
Agents landing on this repo: start at AGENTS.md (root-level, auto-read by Copilot / Claude Code / dsh), then the closed-loop example plugin/CASE_STUDY.md or Discussion #38, and the one-glance contract mcp/AGENT_GUIDE.md.
Compatibility release status
The 0.91.1 release candidate includes DSH 0.2.1-rc.2 compatibility, with
0.1.0-rc.6 / 0.2.0-rc.2 / 0.2.1-alpha.3 coverage retained. npm was still at
0.90.0 when this candidate was prepared on 2026-10-18. Check the
delivery record and
npm view dsh-quant version before treating the fix as published.
Original compatibility contribution: @hufeide (#136); user reports:
@ziladan (#139 / #140).
The v0.91.1 tag is fixed to the reviewed source. Its first authenticated
publisher attempt failed with npm E404, so the tag is not evidence of npm
availability. See delivery attempt.
Maintainers can manually run release acceptance with source=candidate
to reproduce the Linux package, or source=registry after publication to
verify four clean real-Loader consumers. The workflow never publishes.
Quick Install (dsh users)
npm i dsh-quant
Add one line to your cordis.yml:
- name: 'dsh-quant'
59 tools auto-register — indicators / backtests / factors / risk / fund simulation /
ecosystem metrics out of the box. One quant_research_pipeline runs the whole
PDAT→PET chain. ML/DL knowledge: docs/ML_GUIDE.md;
executable demo: npx tsx demos/ml-workflow.ts.
🚀 Product Experience: Three Minutes to a Full Quant Pipeline
Right after install, experience the complete PDAT→PET flow (BTC public data + simple strategy + backtest + paper trading):
data(quant_market_fetch) → quality(quant_data_quality) → factors(quant_factor_evaluate)
→ backtest(quant_backtest) → metrics(quant_metrics) → risk(quant_risk)
→ drawdown(quant_drawdown) → paper sim(quant_execute_sim) → fund sim(quant_fund)
→ report(quant_report)
One-liner: quant_research_pipeline(symbol=BTCUSDT, limit=120) returns everything
in one call.
Then plug your own plugins into each module (data sources / alpha / models / risk / execution — everything is a plugin, proposals at Issue #27).
Five-step walkthrough with commentary: docs/ONBOARDING.md · Agent one-glance guide: mcp/AGENT_GUIDE.md
🖥️ UI Workbench (dsh-quant-ui)
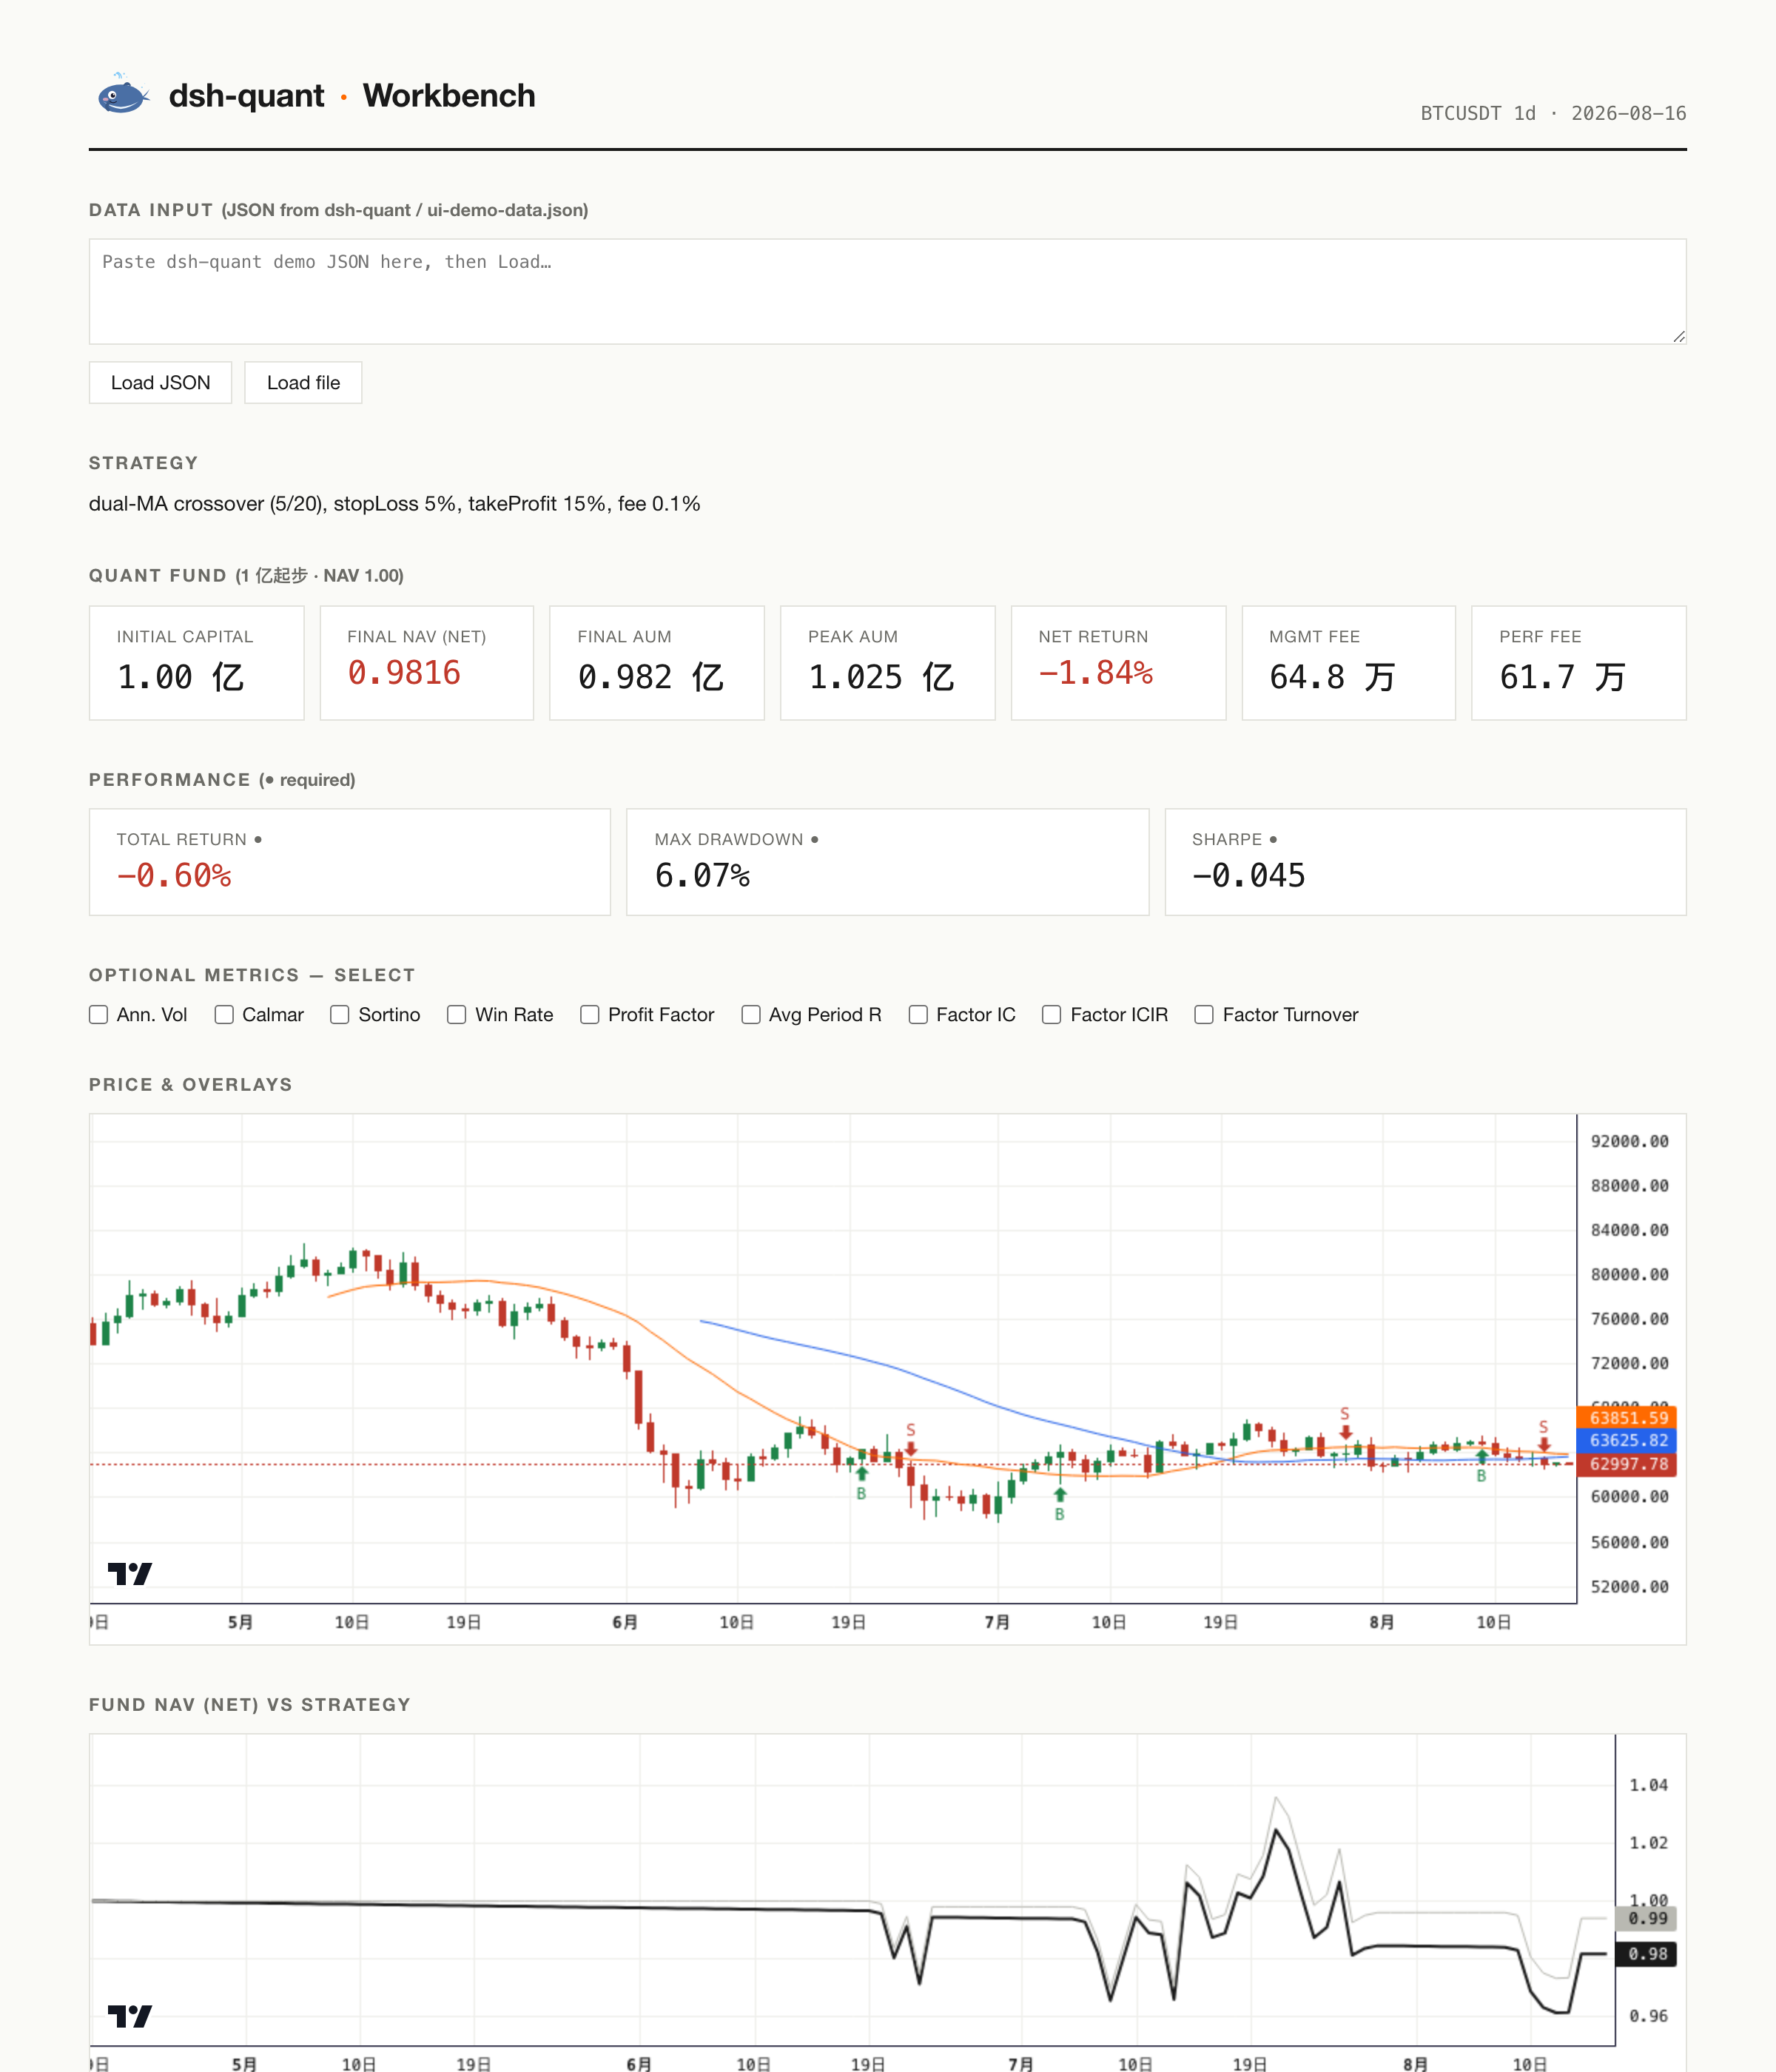
dsh-quant-ui: candlesticks + MA overlays + trade markers, equity curves, fund NAV / management-fee / performance-fee cards, metric selector — plus a swimming chibi whale 🐋 (click the title 3 times).
Live demo: https://dsh-quant-ui.pages.dev
⌨️ CLI (dsh-quant terminal)
Zero-dependency readable terminal (pure Node + ANSI, same philosophy as the P-Research CLI). Browse the research columns and live market data without a browser:
node cli/main.mjs repo                      # 59 tools · 6 domains
node cli/main.mjs history                   # 53 firm archives index
node cli/main.mjs history citadel           # one firm's archive (rendered)
node cli/main.mjs history --reports         # ANALYSIS / TIMELINE / LINEAGE / BANK_LINEAGE
node cli/main.mjs history --search 高频      # cross-archive search
node cli/main.mjs kline BTCUSDT --limit 20  # colored OHLC table + stats
node cli/main.mjs browse                   # interactive TUI: arrow-key firm browser
After npm install -g ., the commands shorten to dsh-quant repo,
dsh-quant history citadel, etc.
Tools
| Tool | Parameters | Canonical output | First valid index |
|---|---|---|---|
quant_data_compare |
dataType (e.g. "financials"/"daily bars") |
{ dataType, channels: [{ name, cost, covers, bestFor }] } (covering first) |
— |
quant_data_advice |
dataType + budget (free/low/institutional) + purpose (research/backtest/official) |
{ recommendations: [{ rank, name, reason }] } (decision-tree ranked) |
— |
quant_series_stats |
values: number[] |
{ count, mean, std, min, max, median, skew, kurtosis, autocorr1, annualizedVol, totalReturnPct } |
— (first step after fetching) |
quant_var_backtest |
returns + varSeries + confidence=0.95 |
{ failures, expected, lrStat, pValue, passed, periods } (Kupiec POF test) |
— (the ground truth for VaR models) |
quant_option |
spot + strike + timeToMaturity + riskFreeRate + type + exactly one of volatility/price |
{ price, impliedVolatility, delta, gamma, vega, theta, rho, … } |
— (Optiver-inspired: BS pricing + five greeks + IV solve) |
quant_volatility |
close: number[] + annualization=252 |
{ annualized, perPeriod, n, logReturns(aligned) } |
— (realized vol; the RV-vs-IV research entry) |
quant_bond |
couponRate + periodsToMaturity + paymentsPerYear? + exactly one of ytm/price |
{ price, yieldToMaturity, macaulayDuration, modifiedDuration, convexity, dv01, … } |
— (FICC link: pricing/duration/convexity/DV01, textbook discounting) |
quant_drawdown |
equity: number[] |
{ underwater(aligned), maxDrawdownPct, currentDrawdownPct, periods(peak/trough/recovery/depth/duration), ongoing } |
— (drawdown episode analysis) |
quant_resample |
candles + period (week=7 bars/month=30 bars) |
{ candles } (OHLCV aggregation, 24/7 markets) |
— |
quant_report |
strategy/metrics/risk/factor/fund (module outputs) | { report } (Markdown research report) |
— (R&D conclusion assembly) |
quant_repo_stats |
owner + repo |
{ stars, forks, watchers, openIssues, openPullRequests, topics, latestRelease, … } (public GitHub API, no credentials) |
— (ecosystem data) |
quant_npm_stats |
pkg |
{ latest, weeklyDownloads, monthlyDownloads, description, … } (npm registry + downloads API) |
— (ecosystem data) |
quant_oss_pulse |
stars + downloadsWeekly? + starsPrevious? + openIssues? + openPullRequests? + daysSinceRelease? |
{ score(0-100), grade(A-D), components, suggestions, summary } |
— (open-source influence score; missing inputs score neutral 50) |
quant_stress_test |
weights + betas + assetVolsPct + correlation=0.6 |
{ weights, scenarioLossesPct, worstScenario, maxLossPct, portfolioVolPct, notes } |
— (portfolio loss under crash/liquidity/vol scenarios) |
quant_risk |
returns (decimal series) + benchmarkReturns? + confidence=0.95 |
{ var95, cvar95, downsideDeviation, maxDrawdownPct, beta, alpha, informationRatio, trackingError, periods } |
— (core risk module) |
quant_fund |
equityCurve + initialCapital=1e8 + managementFeeRate=0.02 + performanceFeeRate=0.2 |
{ initialCapital, finalNavNet, finalAum, peakNav, peakAum, gross/netReturnPct, fees, navNet } |
— (quant hedge-fund sim: NAV 1.00 start, daily mgmt fee, 20% high-water-mark performance fee) |
quant_metrics |
equityCurve + trades? |
{ totalReturnPct, maxDrawdownPct, sharpe, annualizedVol, calmar, sortino, winRate, profitFactor, avgPeriodReturnPct, tradeMetrics } (required trio: return/drawdown/sharpe) |
— (METRIC_CATALOG for UI pickers) |
quant_chart |
kind (candles/series/annotations) + matching data |
structured chart data (dsh-chart protocol: candles+overlays+markers / multi-series / annotation views) | — (UI-route data plane) |
quant_execute_sim |
close + orders[{index, side, quantity?/valueFraction?}] + initialCash? + feeRate? + slippageBps? + latencyBars? |
{ fills, equityCurve, finalEquity, totalReturnPct, totalFee, totalSlippageCost, tradeCount, unfilledCount, cash, position } |
— (execution framework, no live trading) |
quant_trading_cost |
quantity + price + commissionRate=0.001 + spreadBps=5 + annualVolPct=30 + dailyAdv? + participationRate=0.01 |
{ totalCostBps, commissionBps, slippageBps, impactBps, notional, notes } |
— (commission + slippage + market impact) |
quant_trade_quality |
fills (from quant_execute_sim) + unfilledOrders? + holdingPeriodBars? |
{ orders, fills, fillRate, totalSlippageCost, avgSlippageBps, avgHoldingBars, buys, sells, avgFillValue, notes } |
— (execution quality: sim → live expectations) |
quant_research_pipeline |
symbol? + interval? + limit? + provider? + candles? + strategy/fund params |
{ candles, quality, stats, metrics, risk, drawdown, fund, factor, report, charts } |
— (one-call PDAT→PET research) |
quant_factor_evaluate |
factorValues + forwardReturns (factor[i] predicts ret[i+1]) + quantiles=5 + window=20 + decayHorizons=5 |
{ ic, rankIc, icDecay, icir, icSeries, quantileReturns, longShort, turnover, autocorr1, n } (alphalens set + RankIC/IC decay) |
— |
quant_factor_neutralize |
factorValues + groups? + styleFactors? + method? |
{ values(standardized), method, groupCount, styleCount, rSquared } |
— (group z-score / OLS residual neutralization) |
quant_walk_forward |
returns + features[][] + trainWindow + testWindow + step? |
{ predictions(null-aligned), oosIc, oosRankIc, oosCount, windows, trainR2Mean } |
— (rolling train / out-of-sample, no look-ahead) |
quant_rebalance_schedule |
driftPerPeriod + costPerRebalance + maxFrequency=60 |
{ frequencies, totalCosts, bestFrequency, bestCost, costBreakdown, notes } |
— (drift vs cost: optimal rebalance frequency) |
quant_parameter_sensitivity |
baseValue + range=0.2 + steps=9 + metricValues? |
{ paramName, values, metricValues, baseValue, robustness, bestValue, bestMetric, worstMetric, notes } |
— (grid robustness: plateau vs needle-sharp) |
quant_linear_model |
X(samples×features) + y + lambda? + predictX? + yTest? |
{ intercept, weights, lambda, trainR2, n, predictions?, testR2?, testIc? } |
— (standalone OLS/Ridge fit & predict) |
quant_factor_correlation |
factors (equal length) + factorNames? + threshold=0.7 |
{ factorNames, correlationMatrix, highCorrelationPairs, meanAbsCorrelation, effectiveFactorCount, notes } |
— (factor redundancy: dedupe before combine) |
quant_factor_combine |
factors: number[][] (equal length) + weights? |
{ signal(rank 0..1), effectiveWeights, factorCount } |
— (z-score weighting + cross-sectional ranking) |
quant_ic_decay |
factor + returns (same length) + maxHorizon=10 |
{ horizons, icByHorizon, halfLife, bestHorizon, peakIc, peakHorizon, signalType, notes } |
— (IC decay: signal shelf-life → rebalance frequency) |
quant_layered_backtest |
factor + returns (time×asset matrices) + layers=5 + horizon=5 + feeRate=0.001 |
{ layers, topEquity, bottomEquity, longShortEquity, topReturnPct, bottomReturnPct, longShortReturnPct, rebalances, layerMeanReturnPct, notes } |
— (quantile-layer backtest: factor → strategy sketch) |
quant_series_quality |
values: number[], jumpThreshold=0.2 |
{ count, missingCount, zOutliers, jumps, longestConstantRun, healthy } |
— (series-level quality) |
quant_data_annotate |
values: number[], jumpThreshold=0.2 |
{ count, annotations: [{index, label, severity, detail}], summary } |
— (point-level labeling, a tribute to Scale AI) |
quant_data_quality |
candles (quant_market_fetch output) |
{ count, highBelowLow, nonPositive, timeNotIncreasing, timeGaps, extremeMoves, healthy } |
— (pre-analysis health check) |
quant_deflated_sharpe |
observedSharpe + numPeriods + numTrials=1 + skewness? + kurtosis? |
{ observedSharpe, minSignificantSharpe, deflatedSharpe, significant, pValue, notes } |
— (Bailey & López de Prado overfitting-adjusted Sharpe) |
quant_data_pit |
values: (number|null)[] + channels? |
{ healthScore, pit{pass, lookAheadIndices, notes}, survivorship{continuous, gaps, tailTruncated}, channels[] } |
— (AI-infra quality: point-in-time / survivorship / channel reliability) |
quant_channel_guide |
channel (e.g. "akshare") + check? + hasCredentials? |
{ channel, displayName, steps[], prerequisites[], example, fallback, readiness? } |
— (agent-ready channel access guide + readiness check) |
quant_data_guide |
query (channel name/data type, e.g. "tushare"/"financials") or channel (exact name) |
{ query, results: [{ name, url, cost, dataTypes, setup, tutorialUrls, bestFor, … }] } |
— (built-in 15-channel data knowledge base: A-shares/US/bonds + dsh ecosystem data plugins) |
quant_market_fetch |
symbol: string (e.g. BTCUSDT / sh600000 / AAPL), interval: 1m…1M, limit: 1-1000, provider: binance/okx/bybit/sina/tencent/yahoo |
{ symbol, interval, provider, candles: [{openTime, open, high, low, close, volume}] } |
— |
quant_sma |
values: number[], window: integer |
{ values: (number|null)[], window } |
index window-1 |
quant_ema |
values: number[], window: integer |
{ values: (number|null)[], window } |
index window-1 (seed = first-window mean, alpha = 2/(w+1)) |
quant_rsi |
values: number[], window: integer = 14 |
{ values: (number|null)[], window } |
index window (Wilder smoothing) |
quant_macd |
values: number[], fast=12, slow=26, signal=9 |
{ macd, signal, histogram } (equal length) |
macd: slow-1; signal/histogram: slow+signal-2 |
quant_bollinger |
values: number[], window=20, multiplier=2 |
{ upper, middle, lower, window, multiplier } |
index window-1 (population std) |
quant_atr |
high/low/close: number[], window=14 |
{ values: (number|null)[], window } |
index window (Wilder smoothing) |
quant_kdj |
high/low/close: number[], window=9 |
{ k, d, j } (equal length) |
index window-1 (RSV method, K/D seeded at 50) |
quant_williams_r |
high/low/close: number[], window=14 |
{ values: (number|null)[], window } |
index window-1 (range -100..0) |
quant_cci |
high/low/close: number[], window=20 |
{ values: (number|null)[], window } |
index window-1 (±100 overbought/oversold) |
quant_obv |
close/volume: number[] |
{ values: number[] } |
everywhere (first value 0, no nulls) |
quant_adx |
high/low/close: number[], window=14 |
{ adx, plusDi, minusDi, window } |
±DI: index window; ADX: index 2*window-1 |
quant_roc |
values: number[], window=12 |
{ values: (number|null)[], window } |
index window |
quant_backtest |
close: number[], fast=10, slow=30, feeRate=0.001, stopLoss?, takeProfit? |
{ totalReturnPct, maxDrawdownPct, sharpe, position, equityCurve, trades(with exitReason) } |
first trade one bar after first confirmed cross |
quant_backtest_bollinger |
close: number[], window=20, multiplier=2, feeRate=0.001, stopLoss?, takeProfit? |
same (buy on upper-band breakout, sell on mid-band cross-down) | one bar after first confirmed breakout |
quant_backtest_rsi |
close: number[], rsiWindow=14, buyBelow=30, sellAbove=70, feeRate=0.001, stopLoss?, takeProfit? |
same (buy on RSI cross-up through buyBelow, sell on cross-down through sellAbove) | one bar after first confirmed signal |
quant_backtest_portfolio |
assets: [{name, close}], weights?, rebalanceEvery?, feeRate=0.001 |
{ totalReturnPct, maxDrawdownPct, sharpe, equityCurve, assetNames, finalWeights, rebalances } |
— (multi-asset portfolio) |
quant_portfolio_optimize |
returns (time×asset matrix) + method=maxSharpe|minVar|riskParity + iterations? |
{ method, weights, annualReturnPct, annualVolPct, sharpe, assetSharpe, concentration } |
— (weight optimizer; feed result to quant_backtest_portfolio) |
quant_attribution |
returns (time×asset) + weights (sum 1) + factorExposures? [time][asset][factor] |
{ totalReturnPct, assetContributionsPct, assetContribShares, factorContributionsPct, residualPct, factorR2, notes } |
— (portfolio attribution: where did the return come from) |
quant_backtest_grid |
close: number[], fastMin=3, fastMax=10, slowMin=10, slowMax=30, feeRate=0.001 |
{ results(sorted by return desc), best, fastRange, slowRange, feeRate } |
— (grid search; skips fast >= slow) |
Typical chain (model's view)
quant_market_fetch(symbol: BTCUSDT, interval: 1d, limit: 100)
  → take close → quant_sma / quant_ema / quant_rsi / quant_macd / … → quant_backtest
Verified live: real Binance daily bars → indicators → backtest (fast 5 / slow 20) end to end.
Backtest contract
- Dual-MA crossover: buy all-in when fast SMA crosses above slow SMA, liquidate when
it crosses below; signals confirm on bar
iand fill at bari+1close (no look-ahead). - Fees are charged on both sides of notional (
feeRateper side). - Open tail position: the last trade's
exitIndex/exitPrice/returnPctarenull. positionandequityCurvematch input length; equity is normalized (starts at 1); Sharpe is annualized assuming daily frequency (√365).
Alignment conventions
- All outputs are equal-length with inputs; leading unwindowed positions are
null— the model aligns by index, no padding needed. - Empty series or
window > series lengthis a legal result (allnull), not an error. - Non-finite numbers (NaN/Infinity) are rejected at the registry's lossless-JSON
argument snapshot layer (the model's JSON boundary) and never reach
execute. - Constraints (window ≥ 1 integer, macd fast < slow, atr arrays equal length,
multiplier > 0) are hand-checked in
execute; thrown errors becomeisErrorresults via the registry.
Contract (defineTool)
- Arguments use the unified schema DSL, validated by
defineToolbeforeexecute(types / required / integers). executereturns only the canonical JSON value;output.renderproduces the model-facing prose.- Every tool is
isConcurrencySafe: true— pure functions, no shared state, no side effects, parallel-schedulable. - Registration is a reversible effect:
ctx.tools.registerreturns a disposer; fiber disposal unregisters.
Model Experience
What the model sees
Each tool's name/description/JSON schema is injected into the system-prompt assembly
(ctx.systemPrompt.tools()). Descriptions state the alignment rules (which head
positions are null), so the model never guesses.
Token impact
Each tool costs one fixed schema block; call results are charged by rendered content.
The null-alignment design avoids repeated padding requests from the model.
KV cache impact
The schema prefix is stable (reused as long as the tool set and order are unchanged); results append after the reusable prefix.
Release history (NEWS)
| Version | Date | Notes |
|---|---|---|
| 0.91.0 | 2026-09-11 | QRT Deep-mode full due diligence — nine-section rewrite (AUM chain to $50bn, 2025 flagship +30%, QFII+WFOE not QDLP, Dao 98% cumulative since 2022-11, Jaillon premise removed), 5 research dossiers |
| 0.90.0 | 2026-08-23 | HIGHFLYER_SPECIAL — dual-engine king (quant funds AGI, DeepSeek $45B, Wenfeng world AI-richest), 50 reports total |
| 0.89.0 | 2026-08-23 | UBIQUANT_SPECIAL — China AI-transform deep-dive (WorldQuant lineage, IQuest-Coder 40B open source, capsizing paradigm), 49 reports total |
| 0.88.0 | 2026-08-22 | quant_trading_cost + quant_rebalance_schedule — cost gate + drift/cost optimizer (59 tools, 215 unit) |
| 0.87.0 | 2026-08-22 | Validation tools ×4 — factor_correlation / deflated_sharpe / stress_test / parameter_sensitivity (57 tools, 210 unit) |
| 0.86.0 | 2026-08-22 | Bridges ×3 — quant_layered_backtest / quant_trade_quality / quant_attribution (53 tools, 200 unit) |
| 0.85.0 | 2026-08-22 | quant_ic_decay + quant_portfolio_optimize (50 tools, 193 unit) |
| 0.84.0 | 2026-08-22 | AI-infra data modules ×4 — quant_data_pit / quant_channel_guide / CLI quality / chain-loop (48 tools, 186 unit) |
| 0.83.0 | 2026-08-22 | quant_factor_neutralize repaired + 5 baselines (46 tools, 179 unit) |
| 0.82.0 | 2026-08-22 | TYO_QUANT — Tokyo yen-rates-center census (~9 firms, $30M talent war, Capula stronghold), 48 reports total |
| 0.81.0 | 2026-08-20 | CHI_QUANT — Chicago market-making city census (~14 firms, exchange-gene, UChicago pipeline, Citadel exit), 47 reports total |
| 0.80.0 | 2026-08-20 | QUANT_PEOPLE_CN + QUANT_PEOPLE_GLOBAL — 101st-release quant headcount estimates (CN ~30-50k, 4-city ~25-38k, global ~80-120k), 46 reports total |
| 0.79.0 | 2026-08-20 | QUANT_WORLD_MAP — 100th-release special: global quant world map (5-city axis, 9 paths, talent trees, 4-city census synthesis), 44 reports total |
| 0.78.0 | 2026-08-20 | NYC_FOREIGN_QUANT — New York hedge-fund-universe census (~28 firms, 12 HQs, CT suburb dark core, NY-LDN twin), 43 reports total |
| 0.77.0 | 2026-08-20 | LDN_FOREIGN_QUANT — London global-quant-hub census (~30 firms, 12 HQs, four-city comparison), 42 reports total |
| 0.76.0 | 2026-08-20 | SG_FOREIGN_QUANT — Singapore foreign-quant census (~20 firms, crypto/MM/family-office edge, HK twin comparison), 41 reports total |
| 0.75.0 | 2026-08-20 | HK_FOREIGN_QUANT — Hong Kong foreign-quant census (~26 firms, 5 categories, hub-vs-branch, 2025-26 expansion wave), 40 reports total |
| 0.74.0 | 2026-08-20 | QRT_SPECIAL — data-king deep-dive (Credit Suisse MBO, $42B in 10y, Dao China 10×/98%), 39 reports total |
| 0.73.0 | 2026-08-20 | TWOSIGMA_SPECIAL — ML-pioneer deep-dive (DE Shaw spawn flagship, data-first, dual-founder governance crisis), 38 reports total |
| 0.72.0 | 2026-08-20 | DESHAW_SPECIAL — cradle-king deep-dive (computational finance origin, DE Shaw Mafia, Anton supercomputer), 37 reports total |
| 0.71.0 | 2026-08-20 | RENAISSANCE_SPECIAL — black-box-king deep-dive (Simons' three turns, Medallion 66%/30y, $100B+ profits), 36 reports total |
| 0.70.0 | 2026-08-20 | WORLDQUANT_SPECIAL — alpha-factory deep-dive (BRAIN crowdsourcing, 100M alphas, IQC, 101 Alphas), 35 reports total |
| 0.69.0 | 2026-08-20 | SIG_SPECIAL — poker-mother deep-dive (probability OS, ByteDance 15,000×, talent tree root), 34 reports total |
| 0.68.0 | 2026-08-20 | CITADEL_SPECIAL — scale-king deep-dive (dual-engine fund+market-making, $16B peak year, Miami HQ), 33 reports total |
| 0.67.0 | 2026-08-19 | XTX_SPECIAL — per-capita-productivity king deep-dive (£14M/head, six secrets), 32 reports total |
| 0.66.0 | 2026-08-19 | SHOWDOWN_CN_GLOBAL — six-dimension CN-vs-global showdown (+ transparency inversion), 31 reports total |
| 0.65.0 | 2026-08-19 | LISTED_QUANT — listed-quant census (Virtu/Flow/Man + Knight death chain), 30 reports total |
| 0.64.0 | 2026-08-19 | CAPITAL_MODEL — foreign capital-structure census (prop/fundraise/hybrid), 29 reports total |
| 0.63.0 | 2026-08-19 | POD_PLATFORM — pod-shop capstone (5 angles + dsh isomorphism), 28 reports total |
| 0.62.0 | 2026-08-19 | BALYASNY_SPECIAL — sixth firm deep-dive (Schonfeld lineage + 2018 halving + rebuild), 27 reports total |
| 0.61.0 | 2026-08-19 | MILLENNIUM_SPECIAL — fifth firm deep-dive (pod federation + China talent root), 26 reports total |
| 0.60.0 | 2026-08-19 | POINT72_SPECIAL — fourth firm deep-dive (SAC rebirth + Cubist + 14 offices), 25 reports total |
| 0.59.0 | 2026-08-19 | OPTIVER_SPECIAL — third firm deep-dive (Dutch name + Ready Trader Go + tool lineage), 24 reports total |
| 0.58.0 | 2026-08-19 | JANE_STREET_SPECIAL — second firm deep-dive (SIG trio + OCaml culture), 23 reports total |
| 0.57.0 | 2026-08-19 | IMC_SPECIAL — first firm deep-dive special (office chronicle + Prosperity), 22 reports total |
| 0.56.0 | 2026-08-19 | QUANT_VENDORS_CN — China's picks-and-shovels layer (Kafang/RQAlpha/jqdatasdk), 21 reports total |
| 0.55.0 | 2026-08-19 | FOREIGN_CN_MAP_V2 — fully verified foreign-in-China map (7 PFM, second wave 2024-2026), 20 reports total |
| 0.54.0 | 2026-08-19 | Shanghai gravity + foreign-in-China map — SHANGHAI_GRAVITY + FOREIGN_CN_MAP, 19 reports total |
| 0.53.0 | 2026-08-19 | Quant maps ×2 — QUANT_MAP_CN + QUANT_MAP_GLOBAL (city-centric), 17 reports total |
| 0.52.0 | 2026-08-19 | Office maps ×2 — OFFICE_CN + OFFICE_GLOBAL, 15 reports total |
| 0.51.0 | 2026-08-19 | Signature encyclopedias ×2 — SIGNATURES_CN + SIGNATURES_GLOBAL, 13 reports total |
| 0.50.0 | 2026-08-19 | Age chronicles ×2 — AGE_CN (2004-2022) + AGE_GLOBAL (1783-2018), 11 reports total |
| 0.49.0 | 2026-08-19 | D-tier research reports ×4 — REGULATION / TALENT_MAP / STAR_PRODUCTS / QUANT_AI (9 reports total) |
| 0.48.0 | 2026-08-19 | 5 cross-border archives — Tengsheng/Inshiman/Yuansheng/GSR/Eisler (94 firms) |
| 0.47.0 | 2026-08-19 | 8 CN Lite archives — Kaifeng/Honghu/Egret/Zhuoshi/Hande/Niankong/Mengxi/Xinhong (89 firms) |
| 0.46.0 | 2026-08-19 | 7 CN Lite archives — Shenyi/Jasper/Liyi/Bodao/Zunjia/Qianyi/Pingfanghe (81 firms) |
| 0.45.0 | 2026-08-19 | 3 CN Lite archives — Tianyan/Aifang/Maoyuan (74 firms) |
| 0.44.0 | 2026-08-19 | 10 CN Lite archives — Zhicheng/Qianxiang/Blackwing/Inno/LongQi/JoinQuant/Evolution/Sixie/Bridgewater-CN/Beyang (71 firms) |
| 0.43.0 | 2026-08-19 | Golden Bull special — 12 years of quant winners (2014-2025) + archive cross-analysis |
| 0.42.0 | 2026-08-19 | 5 Lite archives — Hongxi/Mingshi/Wenbo/Luoshu/Pansong (61 firms) + founding-date backfill |
| 0.41.0 | 2026-08-19 | Two-mode DD (Deep/Lite) + 3 Lite archives — ChaoQuanZi/YanSheng/Banyang (56 firms) |
| 0.40.0 | 2026-08-19 | DD standard v1 + China batch 1 re-due-diligenced (nine-section format, to-verify lists) |
| 0.39.0 | 2026-08-19 | China batch 2 — Zhixing Tongda/Chengqi/Ruitian/KuanDe/Lingjun/Xiaoyong (53 firms, WorldQuant lineage) |
| 0.38.0 | 2026-08-17 | Bank/brokerage lineage report — 13 firms, two waves, three generations |
| 0.37.0 | 2026-08-17 | China batch 1 — High-Flyer/Ubiquant/Minghong/Yanfu/Century Frontier (47 firms) |
| 0.36.3 | 2026-08-17 | AGENTS.md engagement loop — full vision + ask-your-human CTA |
| 0.36.2 | 2026-08-17 | AGENTS.md + CLAUDE.md agent onboarding |
| 0.36.1 | 2026-08-17 | Five-slot closed-loop case study + 10 supplyable candidates |
| 0.36.0 | 2026-08-17 | plugin/ five-slot external plugin library (22 repos & MCPs) |
| 0.35.2 | 2026-08-17 | Brand line 🐳 Dsh-Quant — The Everything-Plugin Quant OS |
| 0.35.1 | 2026-08-17 | Full English README |
| 0.35.0 | 2026-08-17 | Core UX: PDAT→PET onboarding (BTC example) + mcp/AGENT_GUIDE |
| 0.34.0 | 2026-08-17 | Quant lineage report (five motherships) |
| 0.33.0 | 2026-08-17 | Macro legends batch (42 firms) + first data analysis report |
| 0.32.0 | 2026-08-17 | Systematic Europe batch (37 firms) |
| 0.31.0 | 2026-08-17 | Market-making & crypto batch incl. Alameda failure case (32 firms) |
| 0.30.0 | 2026-08-17 | QRT/Capula/Winton/DRW/Tower batch (27 firms) |
| 0.29.0 | 2026-08-17 | SIG + quant chronicle timeline (22 firms) |
| 0.28.0 | 2026-08-17 | Balyasny/IMC/XTX/Five Rings + DE Shaw boost (21 firms) |
| 0.27.0 | 2026-08-17 | Man Group/AQR/GSA/Bridgewater batch (17 firms) |
| 0.26.0 | 2026-08-17 | Two Sigma/Virtu/DE Shaw/Renaissance batch (13 firms) |
| 0.25.0 | 2026-08-17 | HRT/Point72/Squarepoint batch (9 firms) |
| 0.24.0 | 2026-08-17 | Millennium/WorldQuant/Jump batch (6 firms) |
| 0.23.0 | 2026-08-17 | quant-history + quant-repo columns (Citadel/Optiver/Jane Street) |
| 0.22.0 | 2026-08-17 | Options & volatility board (Optiver-inspired) |
| 0.21.0 | 2026-08-17 | FICC link: quant_bond + bond data channels |
| 0.20.0 | 2026-08-16 | yahoo US/global klines + 13-channel guide + researchMultiAsset |
| 0.19.0 | 2026-08-16 | quant_linear_model + docs/ML_GUIDE + ml-workflow demo |
| 0.18.0 | 2026-08-16 | Chain completion: A-share klines, RankIC/IC decay, neutralization, walk-forward, drawdown, execution sim, pipeline |
| 0.17.0 | 2026-08-16 | dsh-community domain: quant_repo_stats / quant_npm_stats / quant_oss_pulse |
| 0.16.0 | 2026-08-16 | Domain-driven layout ↔ PDAT/PAAT/PCPT/PRT/PET + exchange fallback chain |
| 0.15.0 | 2026-08-16 | Kupiec VaR backtest + resample + report; 100 unit tests milestone |
| 0.14.0 | 2026-08-16 | quant_risk (VaR/CVaR/Beta/Alpha/IR/TE) |
| 0.13.0 | 2026-08-16 | quant_fund (1e8 capital, NAV 1.00, HWM 20% fee) + UI fund cards |
| 0.12.0 | 2026-08-16 | quant_metrics (9+ metrics) + Jane Street-style UI demo |
| 0.11.0 | 2026-08-16 | quant_chart (dsh-chart protocol) |
| 0.10.0 | 2026-08-16 | quant_factor_evaluate / combine (alphalens methodology) |
| 0.9.0 | 2026-08-16 | series stats + data quality + annotation (tribute to Scale AI) |
| 0.8.0 | 2026-08-16 | channel compare + decision-tree advice |
| 0.7.0 | 2026-08-16 | mcp/tools.json + pure-function re-exports + docs |
| 0.6.0 | 2026-08-16 | data channel guide (8 A-share channels) + rename to dsh-quant |
| 0.5.0 | 2026-08-16 | multi-exchange sources (OKX / Bybit) |
| 0.4.0 | 2026-08-16 | multi-asset portfolio backtest (periodic rebalancing) |
| 0.3.0 | 2026-08-16 | strategy family (Bollinger breakout / RSI reversion) + stop-loss/take-profit |
| 0.2.0 | 2026-08-16 | +6 indicators (KDJ / W%R / CCI / OBV / ADX / ROC) |
| 0.1.0 | 2026-08-16 | Launch: market data + 6 indicators + MA backtest/grid + CI/auto-release |
Full records: NEWS.md and CHANGELOG.md.
Known limitations & roadmap
- Market coverage is crypto-first: Binance / OKX / Bybit public APIs (automatic fallback), no credentials; A-shares go through the channel knowledge base (akshare et al. as future providers).
- Backtests are a built-in strategy family: dual-MA / Bollinger breakout / RSI reversion / portfolio rebalancing / grid search; custom strategy callbacks are the future route.
- presentCall/presentResult not customized: indicator results have no file / terminal / diff semantics; UI falls back to generic cards.
- Market tools need network: live cases live in verify.ts; offline indicator / backtest cases are unaffected.
Domain layout (PDAT→PET pipeline mapping)
src/dsh-data/       data (PDAT): 3 exchanges, 15 channels, quality/annotation, resample
src/dsh-alpha/      alpha (PAAT): 12 indicators + factor eval/combine (alphalens methodology)
src/dsh-ml/         portfolio (PCPT): strategy backtests + portfolio + metric catalog
src/dsh-risk/       risk (PRT): VaR/CVaR/Beta/Alpha/IR + Kupiec test + options + bonds
src/dsh-execution/  delivery (PET): chart data plane, fund sim, research report (no live trading)
src/dsh-community/  ecosystem (unique to the open side): GitHub/npm data + influence pulse
The boundary: data and conclusions stay internal; tools and methods ship to dsh-quant — no alpha, no production strategies, no live-trading engineering, but frameworks, indicators, factor evaluation, UI and demos. See pinned Issue #9.
Quick start (after fork/pull)
npm ci && npm run build && npm test    # offline full tests (215 unit + 4 Loader)
npm run test:verify                    # live market integration (needs network)
npm run gen:tools                      # regenerate mcp/tools.json
Build & use
# build lib/ (tsc, NodeNext ESM; ships .js + .d.ts)
cd quant-indicators && tsc -p tsconfig.json

# use in dsh: add one line to cordis.yml
# - name: 'dsh-quant'
# (the Loader resolves the package exports → lib/index.js from node_modules)
Verification
# pure-function numeric correctness + market parsing + backtests (215 cases, node:test, zero deps)
cd deepseek-harness && pnpm exec tsx --test ../quant-indicators/tests/*.spec.ts

# REAL-composition: cordis.yml booted through the real Loader (registration visible / pipeline / isError / HMR-safety)
cd deepseek-harness && pnpm exec tsx --test ../quant-indicators/tests/loader-composition.spec.ts

# harness integration (schemas → execution pipeline → isError → live fetch→indicators→backtest end-to-end)
cd deepseek-harness && pnpm exec tsx ../quant-indicators/verify.ts

# consumer simulation: built lib loaded through real node_modules resolution (simulates post-install)
cd deepseek-harness && pnpm exec tsx ../quant-indicators/consumer-test/boot.ts
⭐ Support
If dsh-quant helps your research, a ⭐ makes the project visible to more dsh users.
This whale stands for DeepSeek Harness (dsh) — trading on its holographic screen 🐋
Issues / PRs / discussions welcome; share your domain perspective in Discussion #10. 🐋
Ecosystem infrastructure: quant ecosystem directory · ecosystem playbook · ecosystem map Discussion #11
Research columns: quant-history (firm archives) · quant-repo (open-source special)
Plugin library (five slots × external repos & MCPs): plugin/
🤝 Contribute & maintain
- Want to add a plugin / data source / learning material? → Issue #109(插件征集) — data / risk / execution plugins, ML-DL & alpha learning resources all welcome
- Filing a bug / feature / help-wanted issue? → ISSUE_GUIDE.md (agent-friendly rules)
- Sending a PR? → CONTRIBUTING.md (dev loop + design contract)
- Maintainer view (how we review & merge): MAINTAINING.md
Every issue is a future PR; every contributor is a future maintainer. We review fast and merge small PRs quickly — credit goes into release notes + the author section. 🐳
👤 About the author
Pengyi Peng — AI-native builder with a mathematics & quant-research background, building this project as an open research sandbox.
- WorldQuant MAPC 2024 · Global 11 / 850 · UK 1 — official Credly badge
- WorldQuant IQC 2024 · Global 232 / 34,142 · UK 5 (finalist)
- dsh-quant: 59 tools · 6 domains · 215 unit tests · 110+ automated releases
- Quant-industry research: 95 firm archives + 53 research reports (in
quant-history/) - GitHub · LinkedIn
Methods open, secrets internal — the author's research is public, the strategies are not. 🐳
Compatibility contributors
Thanks to @hufeide for the DSH 0.2.x adaptation in #136, and @ziladan for requesting 0.2.1-rc.2 verification in #139 / #140. The compatibility audit records tested versions and release boundaries.
Test contribution under review
@Yuren0312 contributed offline market-provider tests in #144 for #106. The independent audit confirms the coverage gain and records one requested Node-type correction. This contribution is under review, not yet merged or shipped.
Related plugins
dsh-weknora
 Tencent
/WeKnora/packages/dsh-weknora
把 WeKnora 知识库接入 dsh 的四个只读工具:列出知识库、混合检索原文片段、按顺序还原单篇文档,以及直接取用 WeKnora 自己带引用的 RAG 或 ReAct agent 回答(含可续聊的 session id)。
dsh plugin --profile web add @wxg-prc-cpg/dsh-weknoratreg
 superdesigndev
/treg
给 Agent 的工具目录:按「要做的事」检索约 2,600 个外部接口(SEO 与 SERP、外链、社交、人物与公司信息补全、广告库、抓取),查看参数与单次调用价格后直接调用,凭据由服务端注入。附带技能,MCP 行在未设置 TREG_TOKEN 前保持禁用。
dsh plugin --profile web add github:superdesigndev/tregdsh-anchored-standard
 xiaobright
/dsh-anchored-standard
两阶段 DeepSeek Harness 预设:先 Minimal 对齐的 bootstrap,再切完整 Standard 工具(Project2 98/99)
dsh plugin --profile web add github:xiaobright/dsh-anchored-standardDeepseek-Harness-EAC
 zouyuxuan122
/Deepseek-Harness-EAC
把官方 deepseek-ai/deepseek-harness(@deepseek-ai/dsh,一切皆插件的 agent harness) 封装为开箱即用的 Windows / Linux 桌面客户端,并在其上拥抱社区万象:皮肤、插件、工具、记忆——你所能想到的,一键皆可装。
dsh plugin --profile web add github:zouyuxuan122/Deepseek-Harness-EACDSHA-dshapp
 DSH-APP
/DSHA/app/src/main/assets/app-integration
DSHA 后台任务、网页返回和草稿恢复适配
dsh plugin --profile web add 'github:DSH-APP/DSHA#a6d4de140acc7a085d6afd4b9d413404e004b939&path:/app/src/main/assets/app-integration'deepseek-harness-remote
 liguobao
/deepseek-harness-remote
基于 DeepSeek Harness 插件机制的多端远程访问方案,让桌面端与 Android 端安全连接并操作远程 Harness。(A multi-device remote access solution built on the DeepSeek Harness plugin system, enabling desktop and Android clients to securely connect to and operate a remote Harness.)
dsh plugin --profile web add github:liguobao/deepseek-harness-remote